Intuit Credit Karma

Screenshots


Details
- Rating
- 441.41K reviews
- Version
- 26.4
- Developer
- Credit Karma, LLC
Analysis by Norviv
When I first opened Intuit Credit Karma, I wanted a simple answer to a practical question: what is happening with my credit, and what should I pay attention to next? The app is a free finance tool from Credit Karma, LLC, built around checking credit information and making its moving parts easier to understand. Its large audience—over 50 million installs and an average rating of 4.7—suggests that many people use it as a regular reference, though popularity alone cannot tell you whether it suits your habits.
I would approach it as a monitoring and learning companion, not as a complete personal-finance system. It can help you notice changes and think through credit-related choices, but it is not a substitute for reading a lender’s terms, checking your own account statements, or contacting a financial institution when something needs correcting. That distinction makes the experience more useful: the app can point you toward a question, while you remain responsible for deciding what to do about it.
What to expect from a credit check-in
Credit Karma is an app in the finance category, and its central appeal is that it turns credit information into something you can revisit without treating every check as a major research project. The dashboard puts score-related details and credit factors in view, while its explanations and educational material help translate unfamiliar terms into everyday language. I find that combination more helpful than a score by itself, because a number gives little direction unless you can connect it to the habits behind it.
The app is free, rated for Everyone, and has been available since February 28, 2013. It has a 4.7 average across around 3.1 million ratings, alongside roughly 441,000 written reviews. The current version is 26.4, and it requires Android 9 or later on Android devices. Those details make it easy to judge basic access and scale, but they do not guarantee that every part of the experience will feel right for you.
For a first-time user, the best expectation is a clearer view of credit, not an instant fix. Score information can help you spot a direction of change, while the factors and learning resources give you a starting point for understanding it. I would avoid treating a single score view as a final verdict on whether a loan, card, or other financial product is right for you; decisions depend on more than one app screen.
Getting Started with Ease
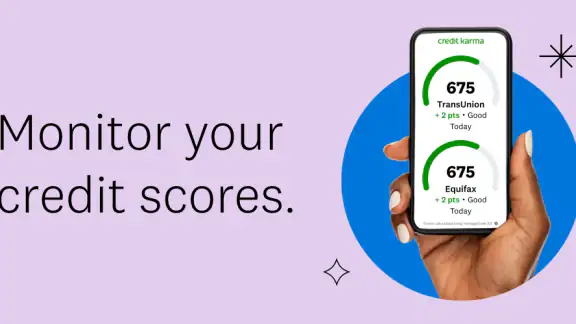
First things first, downloading and setting up Intuit Credit Karma is a breeze. Available on both Android and iOS, it takes a few taps to get started. Once you've signed up, the app does a fantastic job of pulling in your credit information. You get a quick peek into your credit scores from both TransUnion and Equifax. Pretty neat, right?
Making the first check useful
After the initial view, I would take a moment to inspect the factors behind the score rather than stopping at the headline number. Payment history and credit-card utilization are especially useful topics to understand because they connect the report to everyday behavior. The practical payoff is not that the app tells you exactly what to do in every situation; it is that you can identify which detail deserves a closer look before making a change.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
A realistic first-week scenario might be this: you are preparing to apply for a rental, a card, or another form of credit and want to check whether anything in your report looks unfamiliar. Open the app when you have enough time to read, review the information shown, and note any account or inquiry you do not recognize. Then verify details against the relevant financial institution or report source before taking action. That small routine is more sensible than reacting to a notification in a rush.
One useful habit is to compare what you see over time instead of interpreting every movement as a crisis. If the score changes, look at the related information and consider whether a recent balance, payment, or application might explain it. The app can help you notice a pattern, but the context matters: a change is a prompt to investigate, not proof that something is wrong or that a particular product will solve it.
Features that Stand Out
Now, let's talk features because this app is not just about numbers. It goes beyond by offering personalized insights and recommendations. You can see what's affecting your score and get tips on how to improve it. The app's dashboard is intuitive, showing you credit factors like payment history, credit card utilization, and more.
Another highlight is the alert system. It keeps you in the loop with any changes to your credit report. Whether it's a new account opened in your name or a hard inquiry, you'll know about it. Plus, it’s all tailored to you, which makes it feel like you have a personal credit advisor in your pocket.
Alerts are most valuable when you use them as an early-warning cue, not as a substitute for checking the underlying details. If an alert mentions an account or inquiry you cannot place, pause before assuming either fraud or a harmless mistake. Check whether the activity could be connected to an application you made, then contact the relevant institution through a channel you trust if it still does not make sense. This is a more reliable workflow than tapping through quickly and forgetting what prompted the alert.
Personalized recommendations deserve the same careful reading. They can introduce options worth comparing, but a recommendation is not automatically the best choice for your circumstances. Before acting, compare the terms and costs with alternatives and ask whether the product addresses your actual need. If you are trying to reduce debt, for example, a new offer should be judged against your budget and repayment plan, not just its presence in the app.
Understanding the trade-offs
The main convenience is having credit information, explanations, and alerts gathered in one place. Compared with checking individual bank or card apps, Credit Karma is more focused on credit monitoring and education; those financial accounts remain the place to confirm balances, payments, and transactions. Compared with a general budgeting app or a spreadsheet, it gives more attention to credit factors, but it is not the tool I would choose to track every household expense or build a detailed monthly budget.
That difference matters if you already have a routine. Someone who mainly wants to categorize spending may be better served by a budgeting tool. Someone who needs authoritative details about a particular account should go directly to the lender or issuer. Credit Karma is strongest between those tasks: it offers a convenient overview and helps you decide what deserves a closer check, rather than replacing every financial service you use.
There is also a potential attention cost. Regular check-ins can build awareness, but watching a score too often can make ordinary fluctuations feel more important than they are. I would choose a sensible review rhythm and let alerts bring attention to notable changes, instead of opening the app repeatedly for reassurance. The aim is to make calmer, better-informed decisions, not to turn a score into a daily mood gauge.
Educational and User-Friendly
One thing that really struck me is how educational the app is. It doesn’t just give you the numbers; it helps you understand them. There are plenty of articles and resources available to help you get a grip on financial literacy, which is a big win if you ask me.
The user interface is another win. It's clean, straightforward, and easy to navigate. You don’t need to be a financial guru to make sense of it, which is a relief. Everything you need is just a tap away.
For a newcomer, the learning material is most useful when you read it alongside a specific question from your own report. If a factor is unfamiliar, look up what it means, then return to the relevant screen and decide what you can realistically control. That turns general financial education into a focused learning loop, instead of browsing articles without knowing how they relate to your situation.
I would also keep a private note of questions that need follow-up, such as an account detail to verify or a term to research. That is particularly helpful if you are checking the app between errands and do not have time to investigate immediately. A note gives you a concrete next step without relying on memory, and it keeps the app’s overview separate from the records you may need when speaking with a lender.
Who will get the most from it
I think the app is a good fit for someone who has never paid close attention to credit and wants a less intimidating place to begin. It can also suit people who already understand the basics but want a convenient way to review credit information and receive alerts. The educational approach makes it easier to move from “my score changed” to “what should I check?” without needing to start with a technical guide.
It is less suitable as a sole source for people who need a complete view of cash flow, investment accounts, or every financial transaction. It is also not the right tool for someone who prefers not to use an app for sensitive financial tasks or who wants advice tailored to a complex situation. In those cases, direct account providers, a dedicated budgeting method, or a qualified professional may be a better fit. You can still use Credit Karma as a limited reference, but there is no need to make it the center of your finances.
A useful question to ask before signing up is what you want to accomplish first. If the answer is “understand my credit report and notice changes,” the app has a clear purpose. If you expect it to resolve disputed information automatically, manage your monthly spending, or tell you which financial product to choose, the experience may not meet that expectation. Starting with one modest goal makes it easier to judge whether its tools are genuinely helping.
Making Credit Management a Habit
One of the things I love about this app is how it encourages regular check-ins. It’s almost like having a fitness tracker but for your credit. The more you engage, the better you understand your financial health. And with the app's nudges and reminders, you’re less likely to slack off.
To keep that habit useful, I would pair each check-in with one question: did anything change, and is there a sensible action to take? If there is no new information, close the app and move on. If there is a change, identify whether it calls for verification, a conversation with a financial institution, or simply patience. This approach makes the routine purposeful without turning it into constant score-watching.
For someone rebuilding confidence after a confusing credit experience, that small structure can matter. You can use the dashboard to orient yourself, educational material to clarify unfamiliar language, and alerts to notice something that merits attention. The limitation is that the app cannot make a difficult financial decision easy by itself; a repayment plan, a corrected report, or a product choice still calls for careful judgment outside the dashboard.
What to do when something looks off
If information looks unfamiliar, resist the urge to make a quick assumption. First, check whether a recent application or account activity could explain it. Then compare the details with records from the institution involved. If the item still appears wrong, use the appropriate reporting or customer-support route for that institution or credit information source. Credit Karma can help you spot the issue, but checking the source is the step that turns a concern into a useful response.
The same caution applies when a score does not move as quickly as you hoped. A recommendation or article may explain a general factor, but progress depends on the full circumstances behind your credit history and on actions taken over time. I would use the app to learn and monitor, not promise myself a particular result by a particular date. That expectation is more realistic and helps prevent unnecessary applications or rushed decisions.
My recommendation for a first-time user
To wrap it all up, Intuit Credit Karma does a stellar job of simplifying credit management. It's user-friendly, educational, and provides all the tools you need to keep your credit in check. So, if you're like me and want to stay on top of your financial game, give it a whirl. Trust me, your future self will thank you.
My practical suggestion is to begin with one deliberate session: review the dashboard, read about a factor you do not understand, and make a note of any detail that needs verification. After that, let alerts and occasional check-ins support your routine rather than dictate it. Credit Karma is free, approachable, and focused enough to be useful for credit awareness, but I would pair it with your financial institutions’ own records and a separate budgeting method if you need a fuller picture.
Overall, I would recommend it to someone who wants a friendly first step into credit monitoring and is comfortable using an app for that purpose. I would skip it as a primary tool if what you really need is detailed budgeting, direct resolution of account issues, or personal financial advice. Used for what it does best—helping you notice, understand, and follow up on credit information—it can make an otherwise confusing subject feel much more manageable.
Frequently Asked Questions
01What is Intuit Credit Karma and how does it work?
Intuit Credit Karma is a financial management app that provides users with free access to their credit scores and reports. The app analyzes your credit profile and offers personalized recommendations to improve your credit health. It also provides insights into financial products like loans and credit cards that might suit your needs, making it a comprehensive tool for managing your financial well-being.
02Is Intuit Credit Karma really free to use?
Yes, Intuit Credit Karma is completely free to use. The app generates revenue through partnerships with financial institutions, which pay a fee when users apply for financial products through the app. This allows Credit Karma to offer its credit monitoring and financial planning services at no cost to users, ensuring access to essential financial information without any hidden fees.
03How accurate are the credit scores provided by Intuit Credit Karma?
The credit scores provided by Intuit Credit Karma are based on your TransUnion and Equifax credit reports. While these scores are generally accurate, they may differ slightly from the scores used by lenders due to variations in scoring models. Nonetheless, Credit Karma offers a reliable and up-to-date snapshot of your credit health, which can be invaluable for monitoring changes and planning improvements.
04Is my personal information safe with Intuit Credit Karma?
Intuit Credit Karma prioritizes user security by employing robust encryption protocols and security measures to protect your personal information. The app adheres to stringent data protection standards and does not sell your personal information to third parties. Users can feel confident that their data is handled responsibly, with privacy and security being top priorities.
05Can Intuit Credit Karma affect my credit score?
Using Intuit Credit Karma to check your credit score does not affect your credit score, as it performs a soft inquiry. Unlike hard inquiries, which occur when you apply for credit and can negatively impact your score, soft inquiries are non-damaging and are not visible to lenders. This means you can regularly check your credit health without any adverse effects.


